Genval Worldview Fund (1.1.5 - driver-union reweight against snapshot 4.0.3 and alignments 2.0.3; the Fed hiked and the duration shorts grow to -5.19% and -4.40%, energy extends its lead with USO at the top on a shut Saudi pipeline and collapsed corridor talks, gold and the AI complex give back on a 5% ten-year, and net exposure eases 75.9 to 74.9 percent)
Driver-union reweight from  alignments 2.0.3 against
 worldview snapshot 4.0.3 (observedAt 2026-09-16T19:33:57Z). Same seven
wv.active theses, the same 23 holdings and the same fund.method-driver-union as 1.1.4, so this is a patch. Gross 0.9999 (the rounding residual of 23 four-decimal weights), net 0.7489, cash 0.1256.
This is a rotation, not a growth. No holding enters or leaves, so every weight change is a change of view rather than a renormalisation artefact. The movers against a flat book:  KFA Mount Lucas Managed Futures ETF +7.8%,
 Exxon Mobil +7.5%,
 iMGP DBi Managed Futures Strategy ETF +7.3%,
 Chevron +6.0%,
 United States Oil Fund +5.6%,
 iShares 20+ Year Treasury Bond ETF +5.5% and
 iShares 7-10 Year Treasury Bond ETF +5.0% (both shorts growing), against
 VanEck Gold Miners ETF -6.6%,
 SPDR Gold Shares ETF -6.4%,
 Vanguard Total Stock Market ETF -5.9%,
 Intel Corporation -5.8%,
 SPDR S&P 500 ETF -4.8% and the three AI leaders about -4% each. The defense basket is within a point of flat.
The headline is that the regime thesis's prediction was delivered and the book leans further into it.  The FOMC raised the target range to 3.75-4.00% on a 12-0 vote with
 one more hike projected and no cut before 2028, after
 the ten-year closed at 5.00%.
 Hawkish Warsh regime and higher-for-longer stepped 0.89 to 0.93 and the alignment firmed both duration shorts, so iShares 20+ Year Treasury Bond ETF grows to -5.19% and iShares 7-10 Year Treasury Bond ETF to -4.40%. Both remain the most heavily deduplicated positions in the book: their two theses (Hawkish Warsh regime and higher-for-longer and
 Stagflation risk and Fed independence stress) load an identical driver set -
rate-path, monetary-credibility, inflation-debasement - so MAX-within-driver counts each channel once. The hawkish thesis now wins the rate-path and monetary-credibility channels outright while stagflation still supplies the inflation-debasement channel; a naive SUM would size TLT near -9.5%. One caution carried up from the alignment:  the long end rallied four basis points on the decision, and a market that buys duration on a delivered hike is beginning to price the end of the path these shorts express.
Energy extends its lead because its only path to invalidation closed.  Saudi Arabia shut the East-West pipeline after Iraqi-launched drone strikes,
 the Salalah corridor ministerial collapsed, and
 Brent settled $108.75.
 Persistent energy premium stepped 0.85 to 0.90 and this time the equities followed the commodity -
 USO up 3.7%, XOM 3.1%, CVX 1.9% - so every energy leg was marked back up. United States Oil Fund holds the top weight at 7.37% with
 Energy Select Sector SPDR Fund second at 7.15%; the two draw on the same five drivers through their energy and stagflation memberships and dedupe with Stagflation risk and Fed independence stress on
inflation-debasement alone, counted at the stagflation thesis's stronger loading. Exxon Mobil and Chevron are the largest relative gainers among the longs because they serve only the energy thesis and so carry no dedupe against a thesis that eased.
Gold gives back for the reason it gained last time.  Gold structural debasement bid fell 0.89 to 0.86 because
 gold fell to a five-week low on rising real yields and fell again on the hike, and the alignment cut SPDR Gold Shares ETF inside the stagflation basket 0.60 to 0.52 for selling off on the inflation repricing a second time. GLD eases to 5.52% - still third in the book, because its
inflation-debasement and monetary-credibility channels are counted once at the gold thesis's stronger loading and the stagflation membership adds only the rate-path channel. VanEck Gold Miners ETF is the largest relative loser in the book at -6.6% after  the miners fell 5.4% against bullion's 2.3%.
The AI complex is trimmed on cost of capital, not on demand.  AI capex sustained but with China decoupling tail risk eased 0.92 to 0.90 and the alignment marked four of five legs down after
 NVDA fell 5.5% and AVGO 7.6% from September 2 into the 5% ten-year, even as
 Oracle reported 121% cloud-infrastructure growth and $664B of RPO.
 Oracle is the one AI holding that is flat rather than down - the alignment raised it on the densest evidence in the basket while widening its band on
 $28B of quarterly capex, negative free cash flow and a $20B equity raise. The coupling flagged in 1.1.4 stands and is now visible in price: the long AI book (about 21% of gross) and the short duration book (about 10% of gross) are partially the same trade from two ends, and the union does not dedupe them because the AI thesis carries no
rate-path loading. If a future snapshot adds one, both books trim together.
The equity basket rotates toward its downside legs.  Equity melt-up versus building recession risk eased 0.77 to 0.74 and the alignment firmed short
 iShares Russell 2000 ETF and the
 2x Long VIX Futures ETF hedge while easing Vanguard Total Stock Market ETF; the thesis's confidence decline outweighs those strength gains for the hedge, so UVIX still eases 2% while IWM grows 1%. SPDR S&P 500 ETF and VTI trim about 5% each.
 The VIX at 17.20 leaves both invalidation legs unfired.
Theme rollup by gross weight. Energy 23.0% (USO, XLE, XOM, CVX) remains the largest theme. AI 21.3% (NVDA, AMD, AVGO, ORCL, INTC). Defense 13.8% (LMT, RTX, NOC), flat. Gold 13.6% (GLD, IAU, GDX). Equity beta 10.0% long (SPY, VTI, UVIX) against a 2.96% short IWM leg. Duration shorts 9.6% (TLT, IEF). Managed futures 5.8% (DBMF, KMLM). The short book is 12.55% of gross across three legs, up from 12.04%, which is what takes net exposure 75.9 to 74.9 percent.
Holdings
Signed target weights as a fraction of NAV. Green is long, red is short; the bar under each weight is centred on zero.
- fund observed at
- Sep 16, 2026 · 7:56 PM UTC
- derived from snapshot
- Macro worldview (4.0.3 - Wednesday September 16 FOMC-day patch - the Fed raised the target range 25bp to 3.75-4.00% on a 12-0 vote, the first hike since July 2023, with the dots showing one more this year; the 10Y closed at 5.00% on September 15, its first 5% close since 2007; Saudi Arabia shut the East-West pipeline after Iraqi-launched drone strikes and the Salalah corridor talks collapsed, with Brent settling $108.75; August CPI ran 3.4% headline against 2.4% core; gold fell to a five-week low. No thesis added, retired or invalidated; no invalidation condition fires)
- derived from alignment
- Thesis alignments (2.0.3 - patch refresh against snapshot 4.0.3, the Wednesday September 16 FOMC-day moment - the Fed hiked 25bp on a 12-0 vote with the dots showing one more, the 10Y closed at 5% for the first time since 2007, the Saudi East-West pipeline was shut and the Salalah corridor talks collapsed with Brent at $108.75, August CPI split 3.4% headline against 2.4% core and gold fell to a five-week low; membership unchanged in every basket, the duration shorts firm on a delivered hike, energy equities re-track crude so XLE keeps primary, gold is marked down again inside stagflation, and the AI basket is marked down on cost of capital with Oracle the exception)
- weighting method
 Driver Union
- has holding
 United States Oil Fund,
 Energy Select Sector SPDR Fund,
 SPDR Gold Shares ETF,
 iShares 20+ Year Treasury Bond ETF,
 Lockheed Martin,
 RTX Corporation,
 NVIDIA,
 Advanced Micro Devices,
 Broadcom,
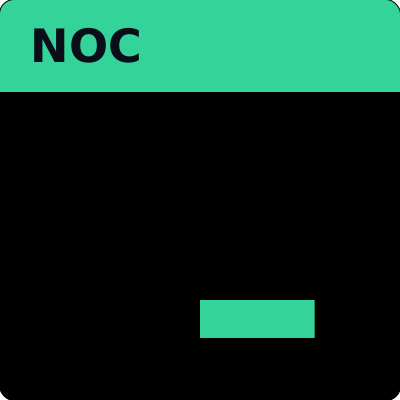 Northrop Grumman,
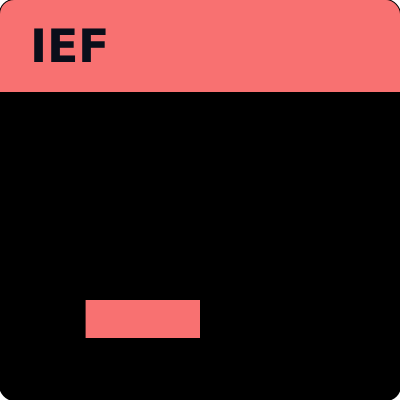 iShares 7-10 Year Treasury Bond ETF,
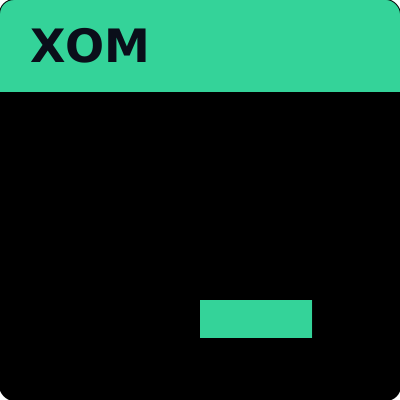 Exxon Mobil,
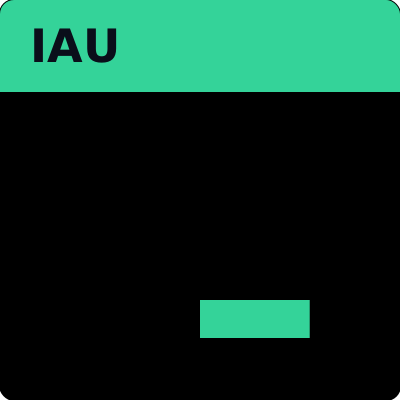 iShares Gold Trust,
 Chevron,
 Oracle,
 VanEck Gold Miners ETF,
 SPDR S&P 500 ETF,
 Intel Corporation,
 2x Long VIX Futures ETF,
 Vanguard Total Stock Market ETF,
 iMGP DBi Managed Futures Strategy ETF,
 iShares Russell 2000 ETF,
 KFA Mount Lucas Managed Futures ETF