worldview.genval.ai
A continuously-updated probabilistic macro worldview — versioned snapshots of theses, confidence, evidence, and the conditions that would break them.
Latest worldview
The current snapshot - every active thesis, its confidence, and what would break it.
Macro worldview (4.1.0 - Friday October 30 minor, four days before the midterms - the defense primes reported record backlogs as PAC-3, Tomahawk and AMRAAM converted to multi-year contracts and LMT rose 23%; Hormuz transits collapsed again, attacks reached their busiest month since March and Brent rose about 13% in October to $114.88; the Fed held 10-2 with two dissents for a hike; Q3 GDP grew 3.4% with core PCE at 3.1%; hyperscaler capex set records without raised outlooks and Alphabet had its worst day on record; gold fell as yields eased. No thesis added, retired or invalidated; no invalidation condition fires)
4.1.0 refresh, taken Friday October 30 ~10:02 AM ET, four days before the US midterms. The window runs from the afternoon of  4.0.5 on October 15 through Warsh's Bangkok remarks, the defense primes' third-quarter reports of October 20-22, the collapse and partial recovery of Hormuz transits, the October 28 FOMC, the hyperscalers' third-quarter capex, and Q3 GDP and September PCE on October 29. This is a minor, because it adds new evidence terms (27), which the protocol versions as a minor; this version was first committed as 4.0.6, never served, and re-versioned before publishing. No thesis is added, retired or invalidated, and no invalidation condition fires. Net moves:
 Iran war rearmament cycle +0.06 to 0.92 (band 0.07 to 0.05),
 Persistent energy premium +0.03 to 0.91 (band 0.06 to 0.05),
 Hawkish Warsh regime and higher-for-longer +0.01 to 0.92 (band held 0.04),
 Stagflation risk and Fed independence stress -0.03 to 0.86 (band 0.06 to 0.07),
 AI capex sustained but with China decoupling tail risk -0.02 to 0.87 (band 0.06 to 0.07),
 Gold structural debasement bid -0.03 to 0.79 (band 0.08 to 0.09),
 Equity melt-up versus building recession risk held at 0.70 (band 0.09).
The rearmament cycle was contracted. Iran war rearmament cycle makes the largest move of the refresh.  Lockheed's backlog rose 27% in a quarter to a record $292B on a $52.5B PAC-3 multi-year award,
 RTX's reached $340B as Tomahawk and AMRAAM framework agreements converted into multi-year production contracts, and
 Northrop's rose to $109.6B.
 LMT rose 23.2%, NOC 13.4% and RTX 6.9% in a window with no US strikes - the market paying for contracts, not escalation.
The strait closed again and the premium was re-struck. Persistent energy premium returns above 0.90.  Hormuz transits fell from 20.8 million barrels on October 8 to 2.9 million on October 11,
 October became the busiest month for attacks since March, and
 Iran claimed four tankers hit mines on October 29.
 Brent rose about 13% in October to settle $114.88, with
 USO up 9.5%. The only movement toward a reopening is
 Vance's framework letter to Rezaei and a Qatari mission to Tehran, alongside a presidential warning to Gulf allies to prepare for strikes after the vote.
The Fed paused with its dissents pointing up. Hawkish Warsh regime and higher-for-longer steps to 0.92.  The FOMC held 10-2, Cook and Hammack dissenting for a hike, with December priced for the next move;
 Warsh called AI investment an inflationary shock; and
 September core PCE rose to 3.1%.
Growth contradicted stagflation's stag half again. Stagflation risk and Fed independence stress eases to 0.86.  Q3 GDP grew 3.4%,
 jobless claims fell to 194,000, and
 Q2 was revised up to 2.2% - an inflationary boom more than a stagflation, with the inflation half intact.
The AI buildout kept spending and lost the market's patience. AI capex sustained but with China decoupling tail risk eases to 0.87.  Hyperscaler capex set records but no company raised its outlook, Microsoft trimmed its year and Alphabet's free cash flow turned negative, and
 Alphabet had its worst day on record as
 the chip complex fell.
Gold fell without the real-yield excuse. Gold structural debasement bid drops below 0.80.  GLD fell 2.0% to
 about $4,025 while
 the ten-year eased about 14 basis points and the Fed paused.
Both equity legs receded. Equity melt-up versus building recession risk holds at 0.70.  The VIX stayed between 15 and 25, peaking at 19.99,
 the S&P stayed below its record, and
 small caps outperformed for the first time in seven windows.
Correction. The BEA's third estimate of Q2 GDP was 2.2%, published September 30; 4.0.4 recorded a 3.0% third estimate released September 24 from secondary search reporting. The original instance is retained and the correction is cited alongside it.
Catalyst calendar. The November 3 midterms end the President's strike pause and decide whether the Vance channel or a short strike comes first, governing Persistent energy premium and Iran war rearmament cycle. October payrolls on November 6 test the labour leg of Stagflation risk and Fed independence stress. The suspended US export-control affiliates rule is due to return around November 10 unless extended - the next scheduled test of the China tail in AI capex sustained but with China decoupling tail risk. October CPI in mid-November and the December 9 FOMC govern Hawkish Warsh regime and higher-for-longer.
Stagflation risk and Fed independence stress
Persistent energy premium
Iran war rearmament cycle
Gold structural debasement bid
AI capex sustained but with China decoupling tail risk
Equity melt-up versus building recession risk
Fed leadership transition policy uncertainty
Hawkish Warsh regime and higher-for-longer
The portfolio it implies
The same theses carried through the alignment into signed target weights.
Genval Worldview Fund (1.1.8 - driver-union reweight against snapshot 4.1.0 and alignments 2.0.6; defense gains about 10% per name on contracted munitions, energy extends its lead through USO on a re-closed Hormuz, and gold, AI and the duration and small-cap shorts give back; 24 holdings, gross 0.9998, net 0.7592, cash 0.1205)
Driver-union reweight from  alignments 2.0.6 against
 worldview snapshot 4.1.0 (observedAt 2026-10-30T14:01:59Z). Same seven
wv.active theses, the same 24 holdings and the same fund.method-driver-union as 1.1.7, so this is a patch with no turnover. Gross 0.9998, net 0.7592, cash 0.1205.
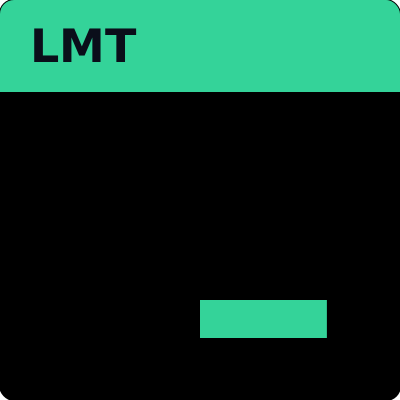
Defense is the largest gain in the book. Iran war rearmament cycle stepped 0.86 to 0.92 on the PAC-3 multi-year and the Tomahawk and AMRAAM multi-years, and the alignment firmed all three primes:  Lockheed Martin 10.2% to 4.88%,
 RTX Corporation 10.3% to 4.72%,
 Northrop Grumman 7.8% to 4.41%. The theme rises from 12.80% to 14.01% of gross.
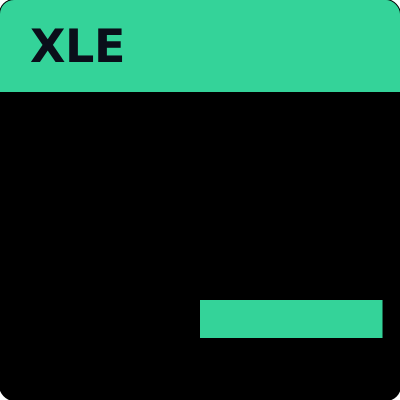
Energy extends its lead, through the commodity. Persistent energy premium firmed 0.88 to 0.91 as the strait closed again and Brent rose about 13% in October. The alignment moved weight toward  United States Oil Fund (2.8% to 7.42%) and away from
 Energy Select Sector SPDR Fund (-2.2% to 7.02%) as the commodity led the producers. The theme is 23.21% against 22.86%.
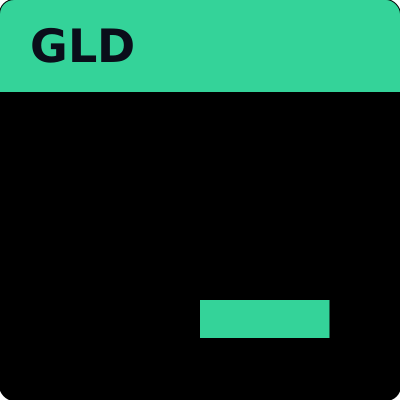
Gold, AI and the shorts give back. Gold structural debasement bid eased to 0.79 and  SPDR Gold Shares ETF falls -5.1% to 4.98%; AI capex sustained but with China decoupling tail risk eased to 0.87 and the AI sleeve falls from 21.08% to 20.67%, with
 Oracle the one AI name up on
 its funding cap. The duration shorts shrink -
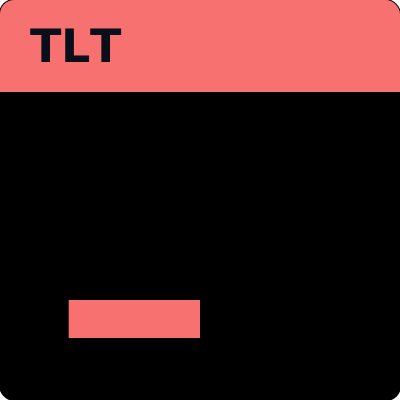
 iShares 20+ Year Treasury Bond ETF to -5.05% - as
 the long end retraced, and the
 iShares Russell 2000 ETF short falls -5.7% after small caps rallied 4.7%.
Theme rollup by gross weight. Energy 23.21% (USO, XLE, XOM, CVX); AI 20.67% (NVDA, AMD, AVGO, ORCL, MU); Defense 14.01% (LMT, RTX, NOC); Gold 12.05% (GLD, IAU, GDX); Equity long 12.24% (SPY, VTI, QQQ, UVIX); Equity short 2.79% (IWM); Duration shorts 9.24% (TLT, IEF); Managed futures 5.77% (DBMF, KMLM). Net 75.9%, up from 75.0% as the short legs shrank.
Holdings
Signed target weights as a fraction of NAV. Green is long, red is short; the bar under each weight is centred on zero.
- fund observed at
- Oct 30, 2026 · 2:38 PM UTC
- derived from snapshot
- Macro worldview (4.1.0 - Friday October 30 minor, four days before the midterms - the defense primes reported record backlogs as PAC-3, Tomahawk and AMRAAM converted to multi-year contracts and LMT rose 23%; Hormuz transits collapsed again, attacks reached their busiest month since March and Brent rose about 13% in October to $114.88; the Fed held 10-2 with two dissents for a hike; Q3 GDP grew 3.4% with core PCE at 3.1%; hyperscaler capex set records without raised outlooks and Alphabet had its worst day on record; gold fell as yields eased. No thesis added, retired or invalidated; no invalidation condition fires)
- derived from alignment
- Thesis alignments (2.0.6 - patch refresh against snapshot 4.1.0, the Friday October 30 moment - record defense backlogs on multi-year munitions contracts, a re-struck energy premium with Brent at $114.88, a 10-2 Fed hold with two dissents for a hike, 3.4% Q3 growth, and an AI sell-off on capex returns; no membership changes, the defense basket firms, USO closes on XLE, ORCL firms on its funding cap, and the duration and small-cap shorts ease)
- weighting method
 Driver Union
- has holding
 United States Oil Fund,
 Energy Select Sector SPDR Fund,
 iShares 20+ Year Treasury Bond ETF,
 SPDR Gold Shares ETF,
 Lockheed Martin,
 RTX Corporation,
 Exxon Mobil,
 Northrop Grumman,
 NVIDIA,
 Chevron,
 Advanced Micro Devices,
 Broadcom,
 iShares 7-10 Year Treasury Bond ETF,
 iShares Gold Trust,
 Oracle,
 Micron Technology,
 SPDR S&P 500 ETF,
 VanEck Gold Miners ETF,
 2x Long VIX Futures ETF,
 iMGP DBi Managed Futures Strategy ETF,
 Vanguard Total Stock Market ETF,
 iShares Russell 2000 ETF,
 Invesco QQQ Trust,
 KFA Mount Lucas Managed Futures ETF